An international payroll manager runs compensation for employees and contractors paid across borders. The work means juggling local pay rules, currency conversion, tax withholding, statutory reporting, and payment timing, often all at once. The aim is straightforward: every worker, in every country, paid accurately and on schedule. What sets the role apart is that it owns the decisions that connect those moving parts, not any one of them alone.
Most companies need this role once payroll runs in more than one country and the volume makes informal coordination risky. A dedicated hire usually makes sense when someone inside the company must approve payment files, own audit trails, and make pay decisions that affect compensation strategy across borders. Smaller companies entering their first market often start with a managed provider or an employer of record and bring in a dedicated owner later. This guide explains what the role does, how it differs from neighboring jobs, which skills and credentials matter, what compliance duties sit on each side of a border, how to benchmark pay and compare employment models, and how to hire well. It also covers the questions that come up most often once the role is in place.
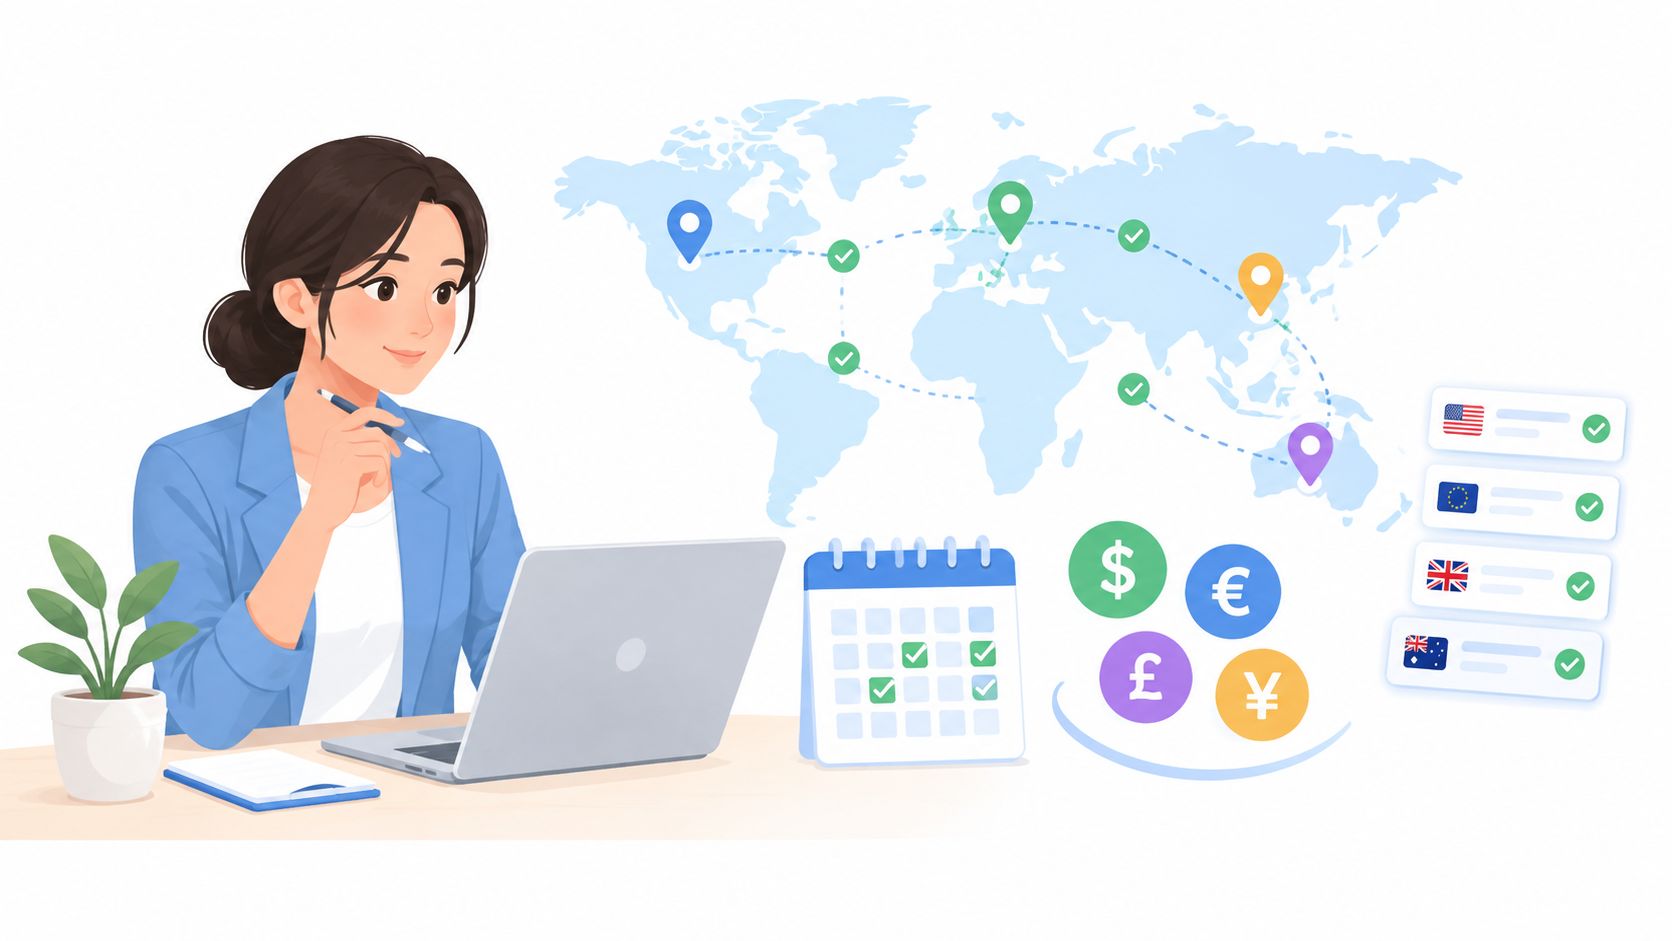
Day to day, the job sits somewhere between payroll mechanics and policy. The manager keeps each country's pay cycle moving, checks that every rate change actually reaches the payment file, and decides how off-cycle corrections get handled. Take a Mexican contractor invoiced in U.S. dollars. That payment can't go out cleanly until a local tax document is on file, and someone has to notice that before the pay date arrives.
Cross-border money matters more than it used to. The World Bank projected that officially recorded remittances to low- and middle-income countries would reach roughly $685 billion in 2024, a figure it said exceeds foreign direct investment and official development assistance combined. Latin America and the Caribbean is one of the largest remittance-receiving regions. For a household that depends on a single transfer, a late or short payment hits hard, so repeatable processes work better than one-off fixes. Read the World Bank's full findings on remittance flows.
Before getting into the details, this table gives a quick view of the role's scope, reporting line, systems, and decision rights. It's a fast way to judge whether the job fits your company's setup.
| Area | What the Role Typically Covers |
|---|---|
| Scope | Pay calendars, currency conversion, local deductions, and payment timing across every country where workers are paid |
| Typical reporting line | Head of Finance, Controller, or COO; sometimes a People lead in smaller firms |
| Core systems | Employee records, payroll calculation tools, bank and FX payment files, and document storage |
| Decisions owned | Pay schedules, off-cycle corrections, filing sign-off, and vendor selection for local advisers |
Most day-to-day questions come back to one of these four areas. If your current gap looks like one of them, the sections below explain how the role differs from neighboring jobs and when it's worth hiring for it.
People often mix this role up with neighboring jobs, but each one owns a different set of decisions. A quick comparison helps:
In practice, that makes the international payroll manager the accountable owner of the whole chain. A company hiring across Latin America, for instance, would expect this person to own the country calendars, approve the final payment file, and decide who is allowed to change a rate. A domestic specialist can be excellent at one country and still lack the authority or the cross-border view to make those calls.
A dedicated hire usually pays off once payroll runs in several countries and the volume justifies a full-time owner. A smaller company entering its first new market often does better with a managed provider or employer-of-record arrangement, since local registration and filing sit with people already set up to handle them. The trade-off is control. An in-house owner sees every rate change before it reaches the payment file, while an outside provider can often get a new country live faster but still needs someone internal to approve the output.
A dedicated role tends to be the right call when:
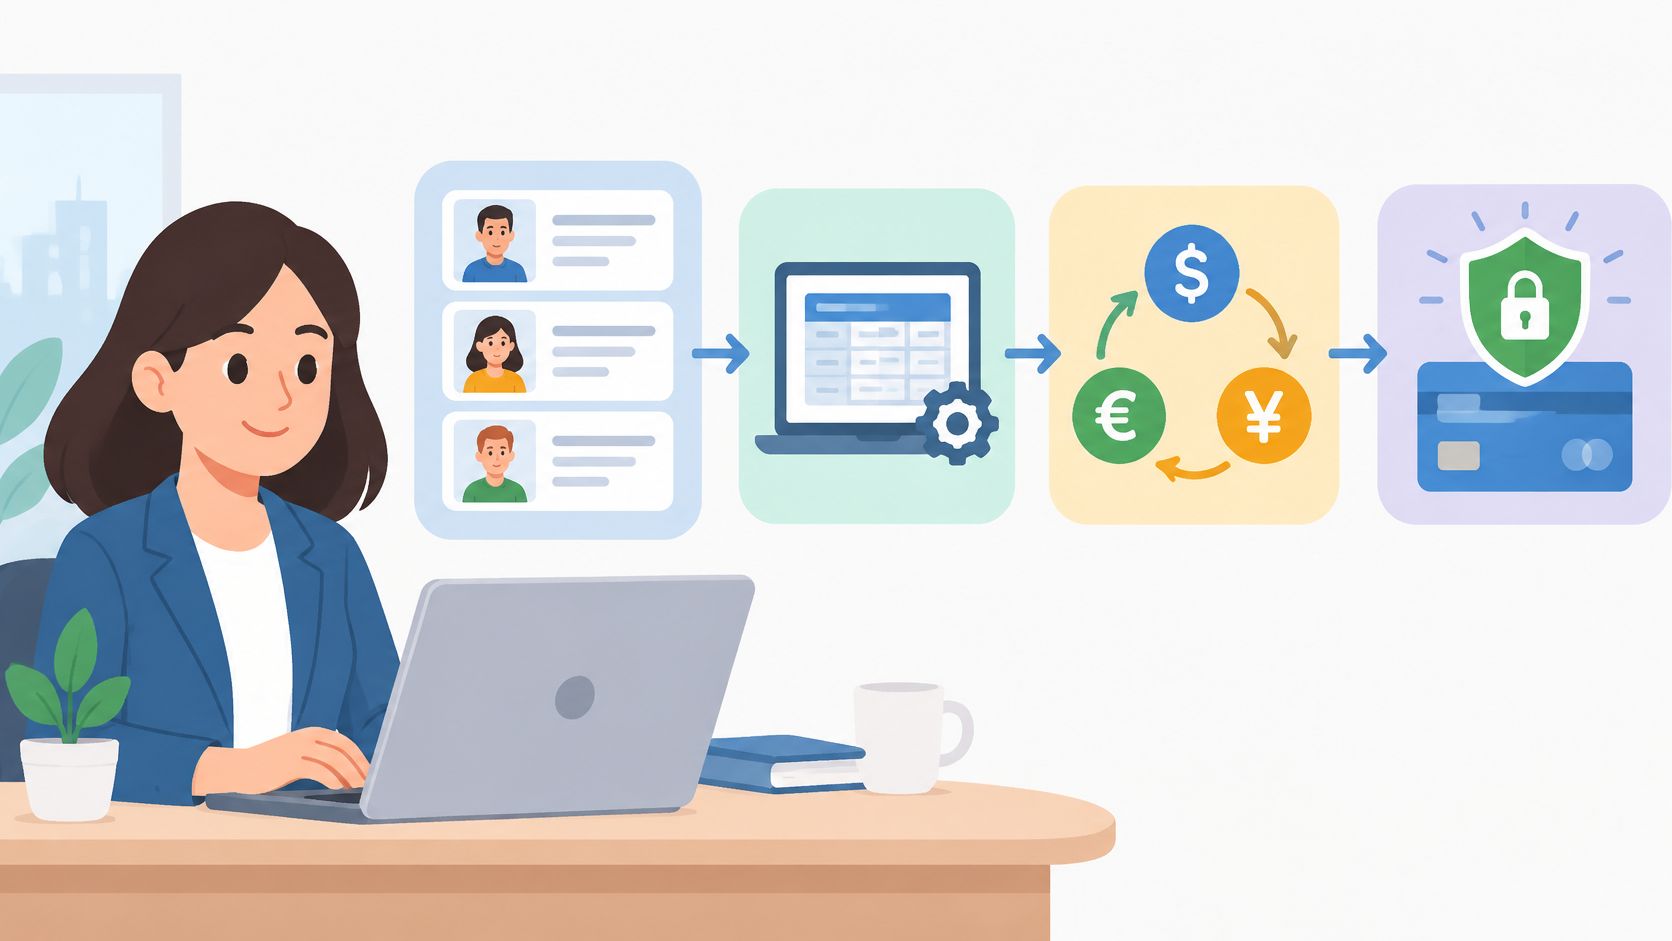
A job posting for an international payroll manager only works if the scope is clear. Breaking the job into four clusters is the easiest way to do that, because it shows what the role owns and what a provider might take on instead.
This cluster covers the day-to-day mechanics of every run. That includes pay calendars, currency conversion, local deductions, and off-cycle corrections. Say a worker's overtime gets missed after the file is already built. The manager has to decide whether it can wait for the next cycle or whether it needs an off-cycle payment. That decision depends on the local rules for timing, the worker's expectations, and the cost of the extra run, so it rarely has a one-line answer.
Compliance work includes filings, year-end reporting, and records of each worker's status. Using the same Mexican contractor example, a local tax document has to be on file before any money moves, so the manager tracks that requirement well before the deadline shows up. Rules differ from country to country, so confirm the details with local advisers rather than relying on a general summary.
Workers tend to ask about pay statements, delayed transfers, and tax lines. Clear answers matter more than fast ones. A good manager never promises a date that a bank hasn't confirmed, because a missed promise damages trust faster than a delay does.
Bank detail changes need extra care. Verifying every change through a second channel is a standard control, since altered payment details are a common fraud target. A request to update an account number that arrives by email should trigger a call to a number already on file, not a reply to the same email thread.
Banks, payroll providers, local advisers, and tax consultants each handle a piece of the process. The manager sets service expectations, keeps an eye on cutoff times, and reviews invoices. Advisers can explain local rules, but the employer remains responsible for the outcome. That's why vendor oversight belongs in the role, even when a provider does most of the processing.
Most payroll errors don't start with one bad calculation. They start with a change that never made it into the payment file.
The role depends on five functional layers, no matter which products a company picks. Knowing what each layer does makes vendor conversations much more productive.
If you want a closer look at how these layers connect, read how international payroll systems fit together.
Consider a Colombian employee who gets a 6% raise effective the first of next month. Ideally, that change moves through every system without anyone retyping it.
Every time someone copies a figure into a spreadsheet, there's another chance for a mismatch. Where a sync isn't available, a single controlled spreadsheet with version history and a named owner is a reasonable fallback, but it should be a stopgap rather than the design.
A ten-engineer startup usually needs a part-time owner. That person oversees a managed provider and approves the monthly payment file, rather than running calculations by hand. An enterprise operating in a dozen countries needs a full-time policy owner. That person sets standards for every jurisdiction, signs off on vendor changes, and runs regular control reviews.
| Company Profile | Typical Role Design | Primary Focus |
|---|---|---|
| Ten-engineer startup | Part-time owner overseeing a managed provider | Output review and payment approval |
| Mid-sized team in several countries | Dedicated manager working with one or more providers | Calendars, filings, and vendor coordination |
| Enterprise in a dozen countries | Full-time policy owner supported by local specialists | Standards, controls, and audit readiness |
When you hire an international payroll manager, a list of past job titles only tells you so much. Strong candidates pair solid technical skill with good judgment. A certification can support both, but it can't prove either one on its own. The sections below cover what to look for, how to structure the process, and how to write the posting.
Start with the work that repeats every cycle. Technical skill is what catches a bad pay file before it leaves your hands.
Judgment is harder to test than technical knowledge, but it matters just as much. A capable manager notices when a problem has outgrown the payroll calendar.
Escalating early is the first test. Someone who flags a missing tax document two weeks before a deadline gives the company room to act. That same problem found on deadline day usually leaves no room at all.
Conflicts between local rules come next. Say a home-country policy grants a benefit that the host country's law treats differently. The manager has to decide which rule governs, confirm the answer with counsel where needed, and write down why.
Explaining delays shows communication skill. A good answer names the cause, gives an expected date, and explains what the worker can do in the meantime. It avoids promising a payment day the bank hasn't confirmed.
A payment delay explained honestly is a manageable problem. A payment delay explained with a guess often turns into a trust problem.
The American Payroll Association (APA) offers two credentials that employers often ask about: the Certified Payroll Professional (CPP) and the Fundamental Payroll Certification (FPC). Both are built around U.S. payroll practice, so read them with that in mind.
| Credential | What It Signals | Limits for Cross-Border Work |
|---|---|---|
| Fundamental Payroll Certification (FPC) | Foundational knowledge of U.S. payroll concepts and recordkeeping | Says little about foreign tax, social contribution, or banking rules |
| Certified Payroll Professional (CPP) | Broader command of U.S. payroll practice, aimed at experienced professionals | Measures U.S. practice only; doesn't confirm experience in any other country |
A certification shows what someone knows about U.S. practice, but cross-border work turns on local detail. Hands-on experience with Mexico, Colombia, or Brazil usually counts for more than a general credential when the workforce is concentrated in those countries. Some companies are better served by local advisers than by one in-house expert trying to cover every jurisdiction. Be realistic about that trade-off before you write a requirement that no single candidate can meet.
Before you put any credential requirement into a job description, confirm the current requirements directly with the APA.
Start by writing down what the role owns and what it doesn't. Decide who signs off on the final payment file, who can approve off-cycle payments, and who is allowed to change a pay rate. If that isn't clear, the new hire ends up carrying responsibility without the power to act on it.
Bring in the finance lead, the HR owner, and whoever reviews tax filings. Each of them touches a different decision. When this step gets skipped, you often end up with a job description that looks complete but gives the person no real approval rights.
List every country where you pay people, then note each pay date and cutoff. Plenty of employers hire for experience in one country, only to find their workforce spans four. Do this mapping before you write a single requirement, because it determines which local knowledge the role actually needs.
Split your requirements into must-haves and nice-to-haves, and tie each one to a real task. "Multi-country experience" tells candidates very little. "Reconciling payroll in two currencies each month" tells them exactly what the job involves, and it helps weed out people who don't fit.
Teams hiring for specialized roles like this one can also speed up sourcing and screening with software. Some recruiters rely on automated follow-up tools for recruiters to keep candidates moving through the pipeline. Automation handles reminders and scheduling well, but the scoring and the final hiring decision should stay with people who understand the payroll work.
Give candidates a short, country-specific scenario, such as a Colombian employee whose pay rate changes halfway through a cycle. Ask them to talk through the steps, the approvals they'd need, and what they'd tell the worker. Strong candidates say what they'd verify before acting. Weaker ones promise a quick fix without checking the facts first. Score each answer against the same criteria so that comparisons between candidates stay fair.
Give each window one clear goal. In days one to thirty, the hire learns the systems and documentation. Days thirty-one to sixty cover vendors and filing deadlines. By days sixty-one to ninety, the person should hold full approval authority. Adjust the timeline if your country list is long, since each additional jurisdiction adds weeks of onboarding with local advisers.
Before finalizing your wording, compare it against how to create job descriptions to make sure the duties and approval rights are described plainly.
Role Summary: Own payroll across [number] countries, from pay calendars and FX conversion through final payment approval.
Responsibilities: Maintain pay calendars, process off-cycle corrections, coordinate local filings, and manage payroll vendors.
Must-Have: Multi-country payroll experience, multi-currency reconciliation, and a documented track record of sound escalation decisions.
Nice-to-Have: Hands-on experience in specific countries, such as Mexico or Colombia.
Tools: Payroll calculation software, bank payment file formats, and a version-controlled document repository.
Compensation: [Salary range from a dated, country-specific benchmark].
Equal Opportunity Statement: [Company name] is an equal opportunity employer and welcomes applicants from all backgrounds.
Every cross-border pay run creates obligations in at least two countries. An international payroll manager has to keep track of both. A rule you satisfy in the United States can still be broken in the country where the worker lives. Treat what follows as general orientation rather than legal advice, since these rules change over time and differ by jurisdiction.
On the U.S. side, the first question is always classification. The IRS applies a common-law test that looks at behavioral control, financial control, and the nature of the relationship. A contractor who works set hours under close direction can start to look a lot like an employee.
When you pay a foreign individual, the payer generally needs a valid Form W-8BEN on file to certify foreign status. If that form is missing, the payer may be required to withhold at a default rate, and the worker ends up with less than expected. Check the IRS guidance on Form W-8BEN before you finalize any foreign payee file.
Reporting is the other piece. Certain U.S.-source payments to foreign persons are reported on Form 1042-S, and which rules apply depends on the income type and the payee's status. Ask your tax adviser to confirm the right forms for each payment type instead of guessing.
Remote teams spread across borders bring legal and administrative duties that an international payroll manager cannot afford to overlook. Most of the surprises tend to come from the foreign side. Local labor law, mandatory benefits, termination rules, and tax withholding all vary by country, and a process designed around U.S. norms rarely transfers cleanly. Policies on remote work and team expectations sit alongside these duties, and a practical starting point for that side of the work is strengthen culture across remote startup teams.
Timing deserves attention too. World Bank analysts have noted that remittance flows slowed in 2023 before a projected recovery in 2024. For many households, a predictable pay date anchors the budget, so a late payment hurts more than the amount alone suggests. Discover more insights about regional remittance flows.
Misclassification is the risk that can hit both countries at once. A worker labeled a contractor in the United States may be treated as an employee abroad. That mismatch can lead to unpaid taxes, missed social contributions, and penalties in one or both places.
Classification tests differ from one jurisdiction to the next, so a label that holds up under one set of rules may fail under another. A contract title alone never settles the question. The IRS and the U.S. Department of Labor both focus on how the work is actually performed, and foreign authorities generally do the same. Revisit the classification whenever hours, direction, or duties change.
Good documentation answers three questions: who the worker is, which terms apply, and where the evidence lives. A solid file usually holds the signed agreement, the relevant tax form, and a record of approval. If you need a working structure, start with how to build a payroll compliance checklist.
Keep these two categories separate in your files. Legal requirements come from tax, labor, and reporting rules. Recommended controls are internal habits that make those rules easier to meet. Mixing them up leads to teams treating a best practice as optional or treating a company habit as a legal mandate.
| Area | Legal Requirement | Recommended Control |
|---|---|---|
| Worker status | Classification must reflect applicable tests | Scheduled reviews by someone outside the hiring team |
| Tax forms | Valid forms on file where required | Expiry tracking with reminders |
| Deadlines | Filings made on time with each authority | Documented approval chain |
Rules change, and the specifics for each country need to be confirmed with qualified counsel or a tax adviser before you rely on any written process. Use the guidance here as a practical starting point for those conversations, not as the final word.
Setting pay for an international payroll manager, or for any remote hire abroad, starts with a number you can defend in a budget meeting. The headline rate on a job board rarely holds up under scrutiny. Build your benchmark from sources you can name and date.
Start with the closest comparable U.S. role. The U.S. Bureau of Labor Statistics publishes wage estimates for occupations such as payroll and timekeeping clerks. Those figures describe domestic pay for a related occupation, so treat them as a reference point rather than the final number, since an international role with authority over multiple countries is a different job.
Next, add regional salary surveys and recent job postings from the target country. Surveys usually break results down by city, seniority, and sector, and the differences can be large. A payroll lead in a capital often costs far more than one in a smaller city. Postings help too, but they show advertised ranges, not what candidates actually accept.
Once the benchmark is set, the employment model determines what that salary really costs. Three options come up again and again in remote international hiring: direct employment through a local entity, an employer of record (EOR), and independent contracting. Each one moves compliance work to a different party.
Direct employment through a local entity gives you the most control, but it also brings the heaviest workload. You have to register as an employer, run local payroll, and file on schedule. Setup alone can push a first hire in a new country past the planned start date.
An employer of record acts as the legal employer in each country. It handles payroll, withholding, and filings, and you pay a service fee on top of salary. You still direct the daily work, but you give up some say over local policy choices.
Independent contracting looks like the lightest setup on paper, yet it concentrates classification risk. A contractor invoice seems simple enough. However, a full-time worker who keeps set hours and takes daily direction can be treated as an employee under local tests. When that happens, the company may face unpaid taxes, missed social contributions, and penalties in the country where the work takes place.
The table below puts the three models side by side. Use it as a quick lookup when you are deciding how much compliance work to keep in-house.
| Employment Model | Who Handles Local Compliance | Administrative Load on Buyer | Typically Suited For |
|---|---|---|---|
| Direct employment through a local entity | Your company, through its registered entity and local advisers | High: registration, payroll, filings, and audits | Teams planning a long-term presence and several local hires |
| Employer of record | The EOR, as legal employer | Moderate: contract management and approvals | Companies making their first hire or a few hires in a country without an entity |
| Independent contracting | The contractor, with limited employer involvement | Low: invoices and payment | Project-based work with clear deliverables and genuine independence |
Most teams choose one model for their first hire in a country and revisit that choice as headcount grows. A contractor who gradually starts working like a full-time employee is the classic case that calls for a rethink. Read the table against your actual hiring plan, not just the cheapest row.
Total cost is where budgets usually go wrong. Base pay is only the starting point. You also need to account for statutory contributions, benefits, bank and foreign-exchange fees, software, and the internal staff time spent managing all of it.
Before you sign anything, check these cost lines:
If nobody budgets the hours spent reconciling foreign payment files each month, the real cost stays hidden.
The lowest headline rate can produce the highest total cost once compliance work is added, so compare models on the full number.
Benchmarks shift by city, seniority, and sector, so no single figure should be treated as permanent. Refresh your numbers at least once a year. That keeps budgets tied to current conditions instead of survey data that has already gone stale.
Not always. Most teams reach the point where a dedicated hire pays off once payroll runs in several countries and someone inside the company has to sign off on approvals and keep the audit trail clean. A small team opening its first market often gets further with a managed provider.
The real question is control versus speed. An in-house manager sees every rate change before it lands in the payment file. A managed provider, on the other hand, can usually get a new country live faster. Outsourcing moves the day-to-day work, but it doesn't move the responsibility, so you still need someone internal who owns the approvals.
An international payroll manager is an internal role. This person owns pay decisions, the payroll calendar, and approvals. An employer of record (EOR) is a third-party company that becomes the legal employer in a country and takes care of withholding, filings, and payments.
In practice, the two often work side by side. The EOR handles local compliance while your manager sets the pay policy. Whether an EOR makes sense depends on local law and the structure of each engagement, so have qualified counsel review the arrangement before you sign anything.
Once the first 90 days are behind you, the focus should move from setting things up to checking that they hold. Most teams concentrate on three areas:
Start with the facts. Pull the audit log and confirm what went wrong, how much it affects, and which workers are involved. From there, work through these steps in order:
Correction rules vary from country to country, so let local advice confirm each step before you act on it.
In most cases, a quick and honest correction costs less trust than a slow, vague one.
An international payroll manager is the person who makes sure every cross-border payment is correct, documented, and on time. The role carries real authority over pay calendars, off-cycle corrections, filing sign-off, and vendor oversight, so the scope needs to be written down before the search begins. For companies paying people in one or two countries, a managed provider or employer of record may cover much of the work. Once payroll spans several countries and approvals need an internal owner, a dedicated hire usually makes sense.
Hiring well depends on practical signals rather than credentials alone. Look for candidates who can reconcile multi-currency payments, escalate problems early, and explain delays honestly. Pair that with a clear compliance structure, a dated salary benchmark, and a comparison of employment models based on total cost. Confirm classification, tax form, and filing obligations with qualified counsel or tax advisers in each country.
Three steps will move your team forward this week: write a scope document that covers duties and reporting lines, list the countries that need local review before your next pay cycle, and decide who holds final payment approval. If you also need pre-vetted Latin American candidates alongside payroll support, LatHire can help. Visit lathire.com to talk through your scope.